How We Helped a Client Rebuild His Records and Challenge HMRC’s Tax Calculations
Client details have been anonymised to protect confidentiality.
When many people receive a letter from HMRC, their first reaction is to panic.
That was certainly understandable in this case.
A client approached ATS Accountants after learning that HMRC had opened a compliance enquiry relating to tax years dating back to 2018/19. HMRC believed income had been received through online food ordering platforms and card payment providers, and assessments had been raised based on information obtained from third parties.
The difficulty was that several years had passed. The client had experienced significant personal challenges during that period and had spent a long time outside the UK. As a result, correspondence from HMRC had not been dealt with at the time it was originally issued.
By the time he came to us, he was understandably worried that a substantial tax bill was inevitable.
Fortunately, that wasn’t the end of the story.
Starting With Questions, Not Assumptions
One of the most important lessons from this case is that HMRC’s calculations are not always the final answer.
The client’s first instinct was to assume HMRC must be right. Our first step was to ask questions.
After reviewing HMRC’s correspondence, we wrote to HMRC requesting a detailed explanation of how their figures had been calculated. Before agreeing with any assessment, we wanted to understand exactly what information HMRC had relied upon.
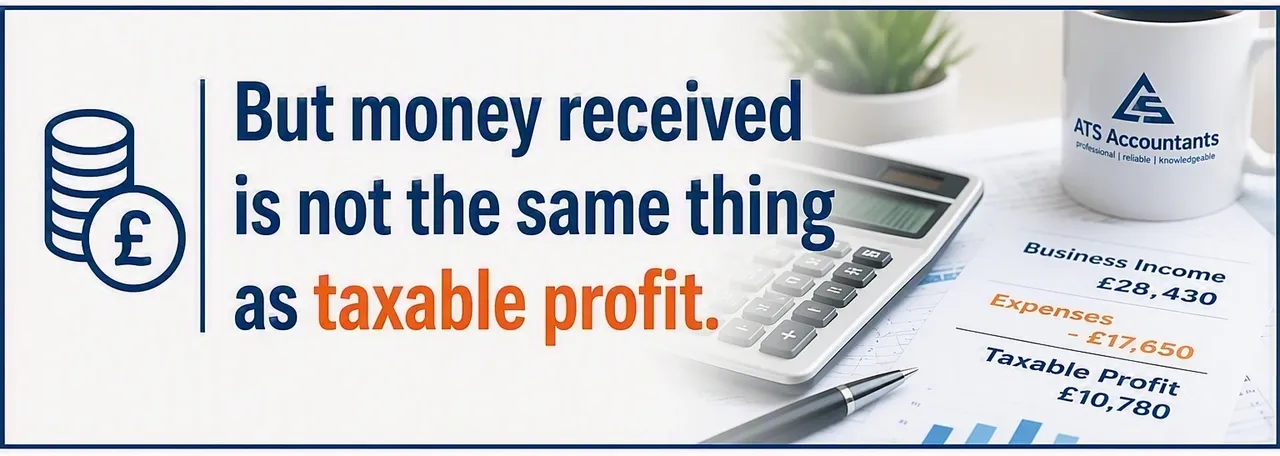
HMRC subsequently provided a breakdown showing sales income identified from online ordering platforms and payment processors, amounting to approximately £28,430 over the three tax years under review. The figures represented money received.
But money received is not the same thing as taxable profit.
Looking Beyond the Income
Like many small business owners, the client had not kept perfect records. That is more common than many people realise, particularly when several years have passed. However, a lack of perfect records does not mean you simply accept whatever figure HMRC puts forward.
We worked with the client to piece together what had happened.
- Receipts were recovered.
- Supplier invoices were located.
- Employment records were reviewed.
- Historical information was gathered from several different sources.
What gradually emerged was a much clearer picture of the business than HMRC had initially seen.
If you’re in a similar position, get in touch with ATS Accountants’ qualified and experienced team –
The Missing Piece: Business Expenses
HMRC’s figures focused on sales income. Our focus was on taxable profit.
The client had incurred genuine costs whilst running the business, including food purchases, insurance costs, travel expenses, phone and internet costs, advertising and other day-to-day business expenditure.
Once these costs were taken into account, the picture changed significantly.
We prepared detailed calculations for each year under review, supported by the evidence that had been recovered. The calculations also considered the client’s employment income and available personal allowances rather than looking at the business income in isolation.
Presenting the Case to HMRC
Having reconstructed the records and prepared detailed calculations, we submitted our findings to HMRC.
Initially, we submitted estimated calculations based on the information then available. As further records and receipts were recovered, we prepared revised workings and provided HMRC with supporting evidence and document references to strengthen the client’s position.
Rather than simply accepting HMRC’s assumptions, we were able to demonstrate that the client’s tax position was considerably more complex than a simple list of income receipts.
This is one of our specialisms at ATS Accountants, find out more here HMRC Investigations | Expert Accountant Representation
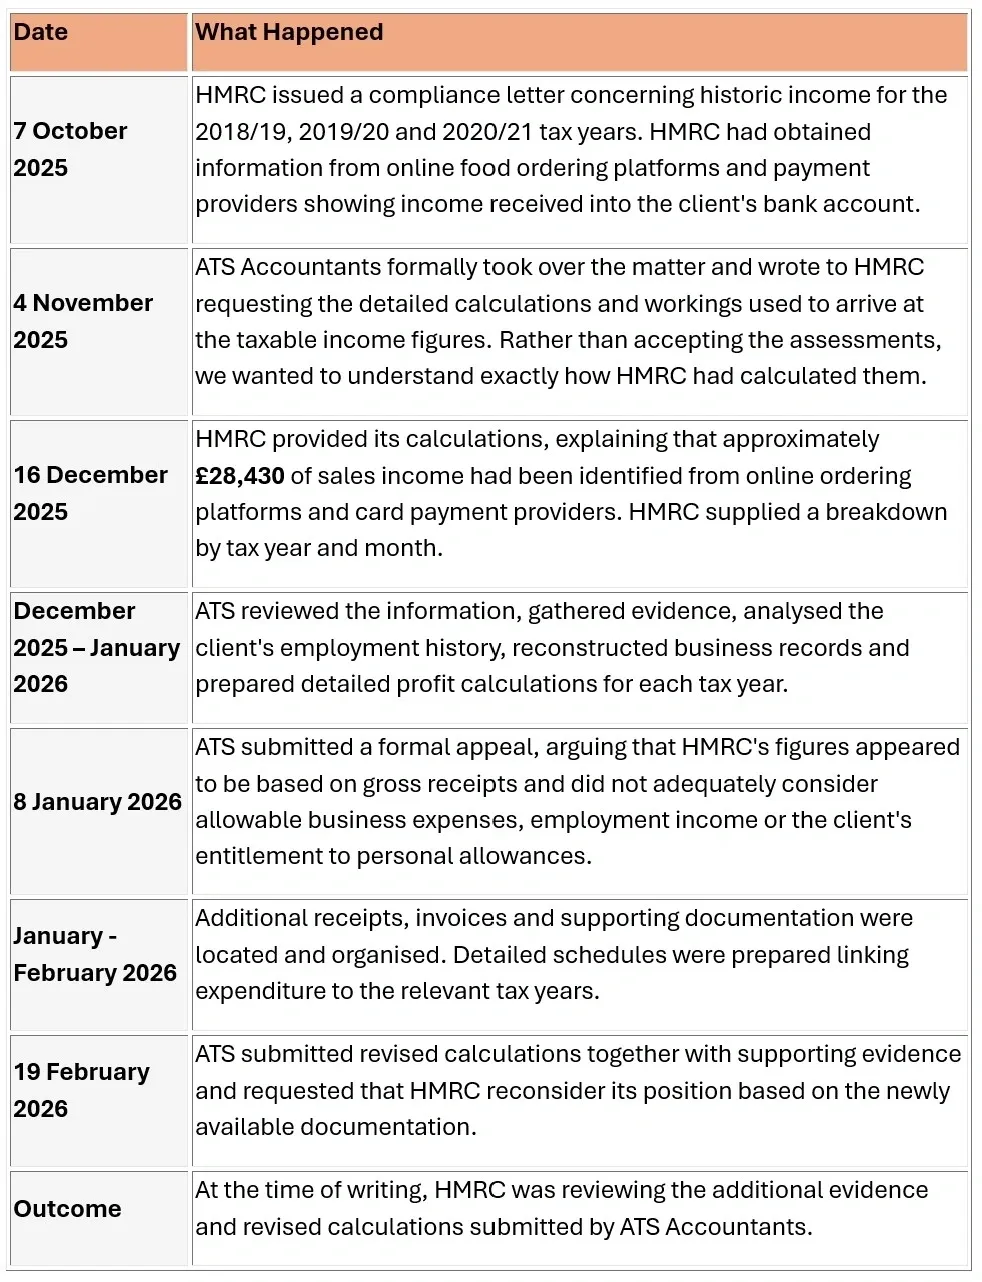
Case Timeline: From HMRC Letter to Formal Appeal
How ATS Accountants helped a client respond to an HMRC enquiry covering historic income from 2018/19 to 2020/21.
What Other Taxpayers Can Learn From This
The biggest takeaway from this case is simple.
1. Do not assume that HMRC’s first calculation is necessarily the correct one.
HMRC has access to more third-party information than ever before. Information from payment providers, online platforms, banks and other sources is increasingly being used to identify undeclared income. However, that information often provides only part of the story.
A proper tax calculation also needs to consider:
- Allowable expenses
- Business costs
- Employment income
- Personal allowances
- The wider circumstances of the individual taxpayer
Had this client simply accepted the figures without challenge, the outcome could have been very different.
2. Don’t Ignore an HMRC Letter
If you receive a letter from HMRC, don’t bury your head in the sand and hope the problem will go away.
The sooner professional advice is taken, the more opportunities there are to resolve matters properly.
At ATS Accountants, we regularly help clients deal with HMRC enquiries, compliance checks, discovery assessments and tax disputes. In many cases, our role is not about arguing with HMRC. It is about ensuring that HMRC sees the complete picture rather than just one part of it.
Sometimes that makes all the difference. If you’ve received a letter from HMRC and are unsure what to do next, ATS Accountants can help you understand your position and communicate with HMRC on your behalf. Contact ATS Accountants
Please also read this real story Received an HMRC Letter About Rental Income? Real Client Story
Further Recommended Reading
Core Accounting Services | ATS Accountants
Tax Planning Services | ATS Accountants
Switching Accountants in the UK: What You Need to Know
Best Accountants in Oldham & Rochdale
About the Author
Shahed Alam BSc (Hons) FCPFA is the Director of ATS Accountants and has extensive experience representing clients during HMRC enquiries, compliance checks and tax disputes.
Throughout his career, he has helped business owners and individuals respond to HMRC investigations, reconstruct historical records, prepare supporting evidence and present robust appeals where appropriate.
Shahed’s approach is built on a simple principle: before accepting any tax assessment, make sure HMRC has the complete picture. This case study reflects that philosophy and demonstrates how professional representation can make a significant difference when HMRC comes calling.